Merchant services for contractors: Addressing cash flow gaps
Managing cash flow can be a challenge for skilled trades businesses, particularly when expenses and incoming revenue don't always line up. Labor, materials and other costs may need to be covered well before customer payments come in—putting pressure on working capital.
While payment timing is only one part of the cash flow equation, how you invoice and collect customer payments can play an important role. A more strategic approach to merchant services for contractors can help you get paid faster, reduce administrative work and gain greater visibility into incoming revenue.
Key takeaways
- The timing and management of small business payment processing is an important operational consideration for skilled trades businesses.
- The gap between upfront project costs and customer payments can create working capital pressure, even for a profitable business.
- A payment strategy that streamlines invoicing can help shorten collection cycles while providing greater visibility into future cash needs.
How cash flow gaps affect skilled trades businesses
Managing cash flow is a common operational hurdle for skilled trades businesses. According to the 2025 Benchmarker report from the Construction Financial Management Association, or CFMA, 40% of contractor assets are tied up in accounts receivable, while only 21% is held in cash.
When you're paying for labor, materials, equipment and subcontractors before you've collected from the customer, even a profitable project can put pressure on your cash flow. And when payment depends on project milestones, inspections, approvals or project completion, this gap can stretch even longer.
Payment delays can add to the pressure. In a 2025 Built survey of US general contractors and subcontractors, 70% said they regularly experience delayed payments, while 35% had seen projects canceled or significantly delayed because of financing gaps. CFMA data also shows that contractors wait an average of 55 days to receive payment.
Changes in final project costs can also further complicate matters. The amount you quote at the start of a job isn't always the amount you ultimately need to collect. Change orders, additional materials, unexpected site conditions and customer requests can all affect the final cost, requiring you to adjust estimates, document changes and keep customers informed along the way.
Where traditional payment processes fall short
How your customers pay can also affect your cash flow. Mailed checks, bank deposits and manual invoice processing can add days—or even weeks—between a finished job and having funds available in your account.
Outdated payment processes also introduce operational pressure. Manually generating invoices, tracking down paper checks, monitoring payment status and following up on outstanding balances all take time away from other areas of your business. And without a streamlined way to manage payments, it can be harder to see what's been paid, what's still outstanding and when revenue is expected to come in.
Improving cash flow through faster payments
Shortening the time between completing work and collecting payment can be one of the most effective ways to improve cash flow management for skilled trades businesses. The longer your cash is tied up, the harder it can be to put it to work elsewhere—whether it means purchasing materials for the next job, making payroll, hiring employees or investing in equipment.
The Built survey underscores the value contractors place on getting paid faster. Among those surveyed, 76% said they'd consider offering a discount in exchange for guaranteed faster payment, while 82% were open to adopting digital payment systems if doing so accelerated cash flow.
Where outdated payment processes can add time and administrative burden, modern payment tools can help remove some of this friction. Digital invoicing, mobile payment acceptance and integrated payment processing can give customers more convenient ways to pay while making it easier to manage invoices and track incoming payments.
A more streamlined payment process can help you:
- Get paid faster by giving customers more convenient ways to pay
- Reduce manual invoicing and collection tasks
- Track outstanding balances and payment status more easily
- Improve visibility into expected cash inflows
- Spend less time on collection-related administrative tasks
Realizing these benefits depends on choosing payment tools that fit the way your business operates.
Aligning payment solutions with how you do business
The right payment solution should reflect how you bill customers, where you accept payments and how your needs may vary across different types of jobs.
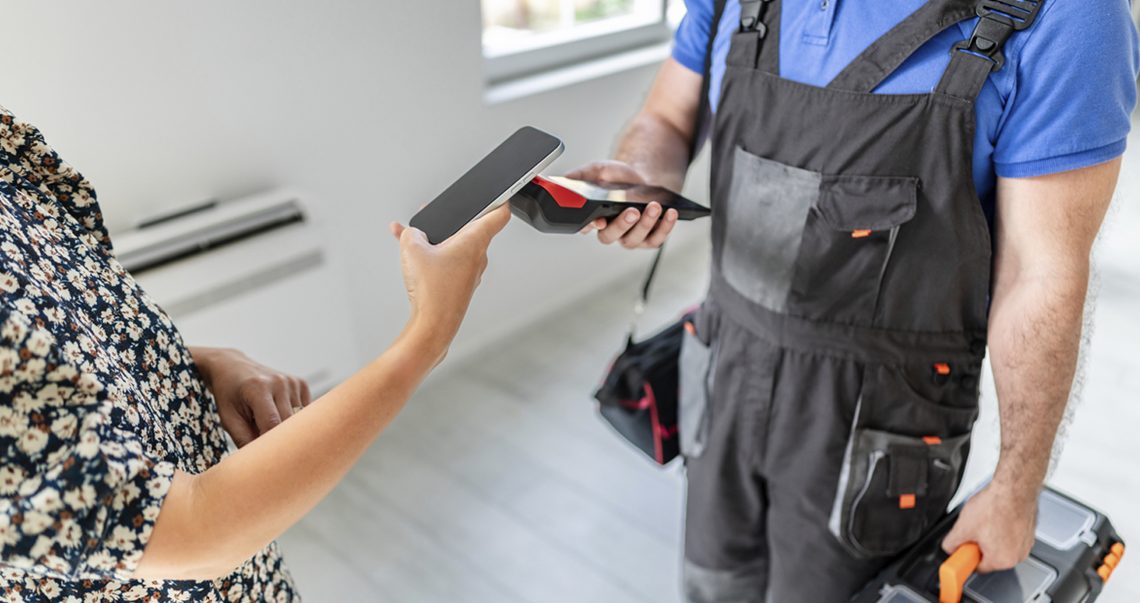
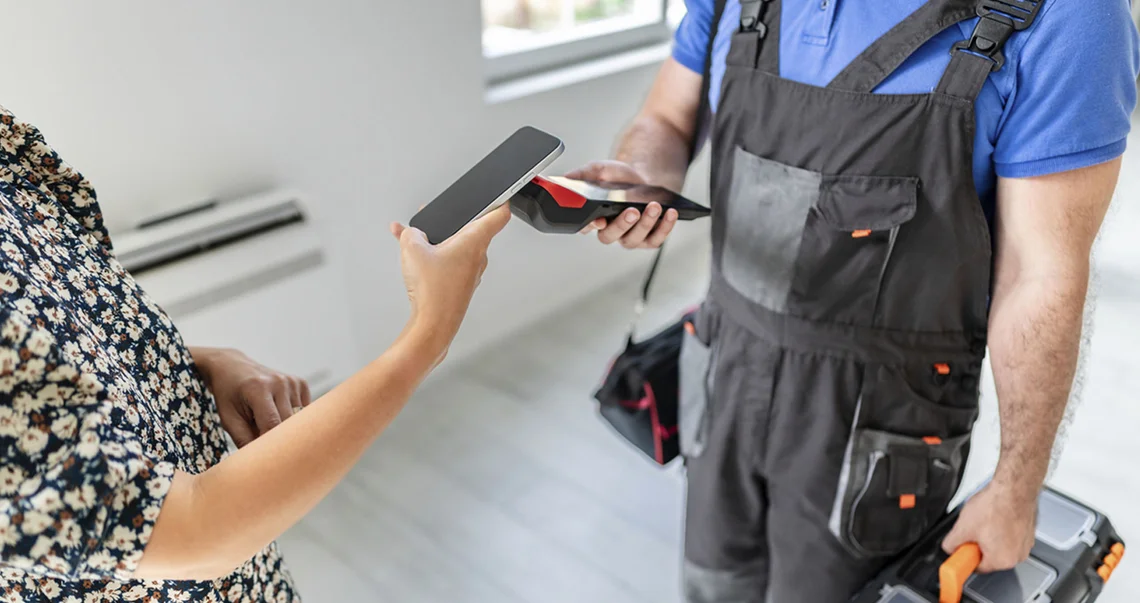
For example, construction and electrical contractors may rely more heavily on project-based billing, progress payments and change orders, while HVAC and plumbing businesses may need the flexibility to accept payment on the spot after completing a service call. Mobile payment capabilities can allow you to securely accept card payments from a phone or tablet while you're in the field, helping to reduce the time between completing the work and collecting payment.
Depending on your business, you may also need to adjust invoices as costs change, accept deposits or recurring payments, or offer different payment options based on the customer or type of work.
The more closely small business payment processing tools align with these workflows, the easier it can be to collect revenue without adding unnecessary steps for you or your customers. When evaluating your options, consider how well they integrate with your existing invoicing and accounting processes, where you need to accept payments, which payment methods you need to support, and how easily you can track transactions and outstanding balances. You'll also want to consider whether the solution can adapt as your business grows, your services expand or your payment needs change.
A strategic approach to cash flow and payments
Accepting and processing payments is only one part of managing how money moves into your business. While a basic payment processing solution may give you the technology to complete transactions, a broader relationship with merchant services for contractors can help you look across the entire payment process—from how and where you accept payments to invoicing, reporting, collections and access to funds.
This broader view can be especially valuable when payment needs vary across jobs and locations. Instead of evaluating individual payment tools in isolation, you can consider how capabilities such as mobile payments, digital invoicing, point-of-sale solutions and transaction reporting work together to make collecting and managing revenue more efficient.
A merchant services specialist can help connect these pieces. By looking across your existing payment and collection processes, they can:
- Evaluate your invoicing and payment collection processes
- Identify inefficiencies that may be slowing down payments
- Select payment solutions that align with your operational needs
- Improve visibility into payment status and expected cash inflows
- Adapt your payment strategy as your business grows or your needs change
"Improving cash flow isn't about making one-off improvements," says Amanda Ostbloom, Merchant Sales Officer with First Citizens Bank. "It's about looking at the full payment process, finding opportunities to make it easier and more efficient to turn completed work into collected revenue, and building a payment strategy that's tailored to the pace and realities of skilled trades work."
The bottom line
Merchant services for contractors are a critical part of reducing the time between completing work and collecting revenue. Getting it right can affect working capital, day-to-day operations and your ability to invest in the growth of your business.
A payment strategy built around how your business operates can help shorten collection cycles, reduce administrative work and give you greater visibility into incoming cash. With the right combination of payment tools and guidance, you can spend less time managing collections and more time focused on running and growing your business.
Ready to get started?
Connect with a First Citizens merchant services specialist to see how you can improve cash flow visibility, streamline collections and reduce administrative work.